
Global Drinks Intel: How do you feel about Campari Group’s first set of results under your leadership?
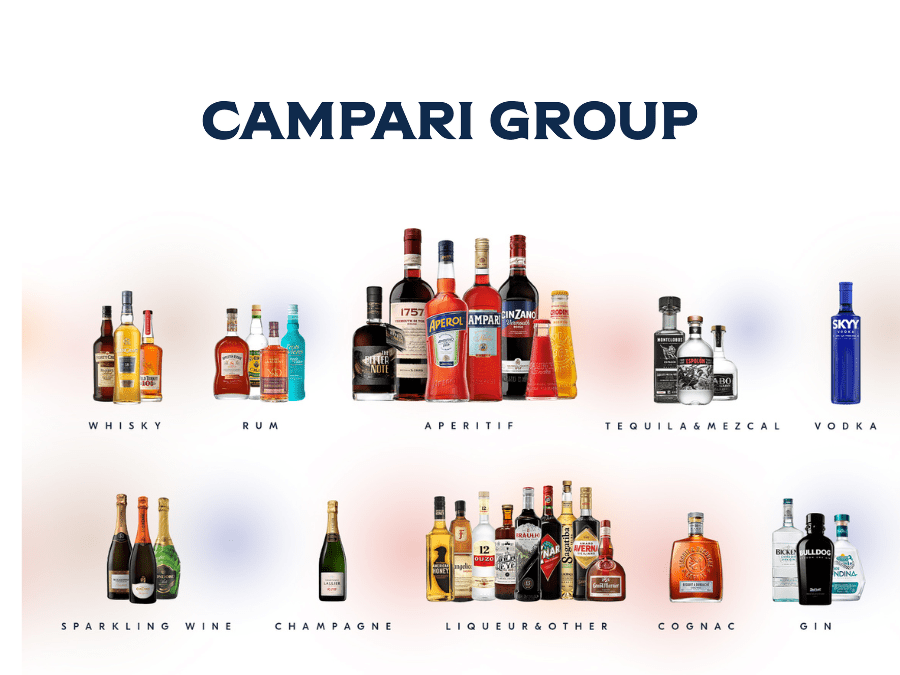
Matteo Fantacchiotti Campari Group CEO: Looking at our current trends – and taking off the buying-forward phasing from (the same three-month period) last year – our growth momentum has continued and we’re delivering what we expected. If I needed to bank on a good start, this is good enough for me. We’re delivering what we promised and the market-share indicators are positive, which means we still have great momentum, especially across our key categories like aperitifs and tequila.
We’re executing our strategy so, so far so good.
GDI: You referenced success for Espolòn tequila in the US as well as the brand’s seeding in other markets.
MF: In the last three or four years, Espolòn has been doing well and was starting to pick up in some other markets.
In my previous job (as ‘Asia Pacific’ MD), I was one of the ones suffering because it was doing particularly well in Australia when suddenly, the group had to put all of the brand’s stock in the US, so we didn’t have enough allocation in Australia and we were out of stock – Italy’s another market like that. Now, we’re finally unconstrained, so we can give all markets the allocation they want. As soon as we restarted activating the brand, especially in Australia and a few others in Europe, Espolòn has started to grow again.
The brand’s in a real sweet spot in terms of price and equity – a liquid that’s extremely good and an image that’s easy for consumers to understand. When we started investing in the brand, it picked up immediately.
We’re lucky to have both Aperol and Espolòn – we’ll be doubling up in terms of investment and activation on those two brands.
GDI: How satisfied are you that the group has tequila’s full price ladder covered?
MF: If you’d asked me that six-to-nine months ago, I would have said we were suffering a bit. Personally, I love to have something in super-premium. Right now, that space is suffering a lot, so I’m quite pleased not to be there. I feel this is temporary and in the long run, this is an interesting space to be.
At the moment, Espolòn is at exactly the right price point in a segment that’s doing well. We don’t need to be aggressive in its promotion; it’s growing naturally.
We also have the Mayenda tequila brand (which was launched a year ago), but only in blanco – a reposado is going to come very soon. We need to be patient, but we’re going to be building Mayenda at around EUR50-EUR60 (US$54-$65) per bottle. We still have a gap in super-premium tequila, but we don’t have a solution there at the moment.
GDI: Have you identified any areas of concern from the quarterly numbers?
MF: We feel pretty pleased – we don’t have any big concerns. Our key brands/markets combinations are doing well and we have good momentum.
The one concern for me – because I care about Asia Pacific – is in explaining the Asia numbers (sales in the ‘Asia Pacific’ reporting region fell by 20.2% in Q1). I wanted to reassure that this is a temporary phasing effect from route-to-market changes, which are going to strengthen our position for the medium term, but are having a short-term impact.
At the same time, I can see in markets like Japan and Korea that we’re still doing really well. In the medium term, Asia Pacific will return to its previous growth trajectory for us.
GDI: How long do you expect this turbulence to last in the region?
MF: China started with a new route-to-market last month, so it should be plain-sailing from this month.
India was supposed to have gone live already, but we had a bit of a delay due to elections, which is typically the case. I would say we’ll be back on track in India from June.
GDI: You’ve closed the Courvoisier acquisition (from Suntory Global Spirits) this month: What are your plans for the cognac brand?
MF: Courvoisier was quite dusty and unloved. From a supply standpoint, the cellar team did a phenomenal job – the factory’s state-of-the-art and there’s a stock of aged liquid that when we did our quality checks and comparisons, is outstanding. We have great stock to leverage.
There was a repositioning of the brand (by Suntory Global Spirits) that I don’t particularly dislike, but we need to understand the position and strategy – they never invested to bring it to life for consumers. There was the start of something, we just need to pick it up in the way that we know how – experiential, liquid on lips – to tell the story.
The brand’s assets are beautiful, the heritage is beautiful and the collection of liquid is amazing. In the medium term, we have an opportunity to transform and unlock a dusty brand into a jewel like it can be. In the short term, we have an opportunity to play with price and margin. Courvoisier is priced too much below its competitors, which is unjustified because the liquid is on par, if not superior.
The mix is also very skewed to VS. It won’t be super easy, but there’s definitely an opportunity to increase activation and consumer penetration for VSOP and XO.
GDI: How will your time as CEO differ from your predecessor’s, Bob Kunze-Concewitz, who stepped aside earlier this year?
MF: Compared to when Bob started, the company today is materially different. There are three things that are going to stay consistently the same: one is the company’s culture, which is very special and we’ll try to protect it. The second is our long-term focus and orientation, and the third is the strategy, which remains to grow both organically and inorganically.
We will still transform the company and I’m not really sorry about that, because I like transformation. We now need to integrate Courvoisier, which is a big priority because it’s our largest ever acquisition. But we’ve been quite vocal that this is not the last (acquisition) we’re going to do – we’re still active on the inorganic front.
GDI: How are you getting on in your first few weeks as CEO?
MF: The changeover wasn’t a big disruption. We had a long handover period – the change was announced in September and I started to get much more involved then. I’m also based here in Milan now. So, I’ve been preparing for months.
We shouldn’t forget that while Bob was the visible part of the group, there was a management team that has been with the company for between 15 and 25 years. Our CFO, Paolo Marchesini, for example, was here before Bob, during Bob and after Bob.
I have quite a solid team that helped to deliver everything that you’ve seen, which is quite a comfort.