The appeal of shopping in the global travel retail channel remains rooted in practical and leisure-driven motivations. According to Swiss research agency m1nd-set, the biggest purchase drivers across all product categories are lower prices than downtown stores or online retailers, followed by the opportunity to browse before travelling, a broad product assortment, convenience and good customer service.
Yet practical benefits tell only part of the story: the lure of exclusivity also plays an important role. GTR-only products, along with limited-edition releases, continue to resonate with travellers. The appeal of these exclusive offerings has remained consistent, hovering between 15% and 17% every year since 2023.
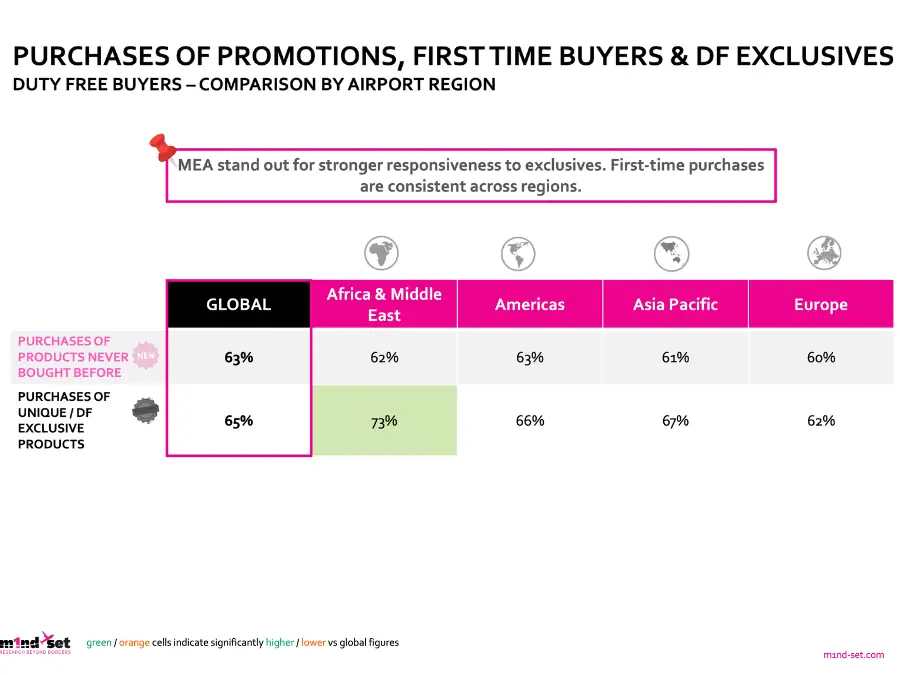
However, m1nd-set’s research reveals a striking gap between what travellers say motivates them to buy and actual purchasing behaviour. While fewer than one-fifth of shoppers globally cite exclusives as a primary reason to shop, once they’re inside the store, the allure of unique discoveries and the pursuit of exclusive rarities become powerful conversion tools.
Nearly two-thirds (65%) of GTR shoppers bought a unique or channel-exclusive product, according to the Swiss research agency. The trend has evolved steadily over the past two years, rising from 57% in 2024 to 66% in the first half of 2026.
The quest for exclusives varies markedly across regions. Travellers from Africa & Middle East lead the way, with 73% snapping up duty free-exclusive products, compared with just 62% of European shoppers.
Travel retail continues to cement its reputation as a powerful platform for discovery, with global shoppers showing a strong appetite for trying something new. More than six in ten (63%) purchased a product they had never bought before while shopping in duty free, highlighting the channel’s unique ability to drive product trial and introduce travellers to new brands.
Understanding the global alcohol shopper
Among alcohol shoppers worldwide, the dynamics of GTR’s appeal look notably different. Price is by far the channel’s strongest purchase driver, finds m1nd-set, with around four in ten alcohol shoppers citing lower prices as the primary reason they buy duty-free – significantly higher than the average across all shoppers in the channel.
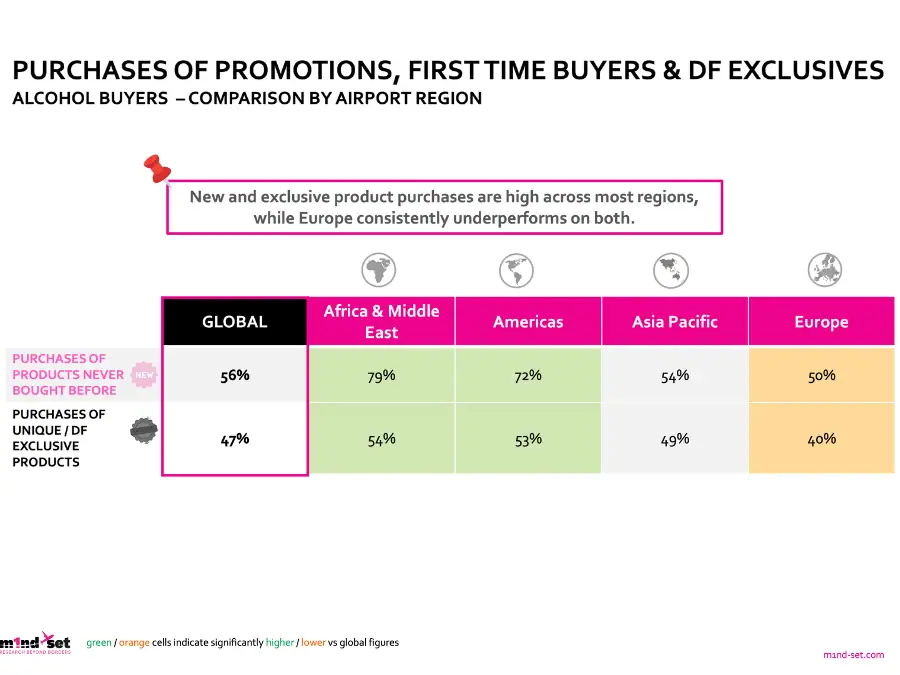
The appeal of duty-free exclusives ranks lower among alcohol shoppers, trailing other factors such as price, convenience and promotional offers. Even so, exclusivity continues to influence purchasing behaviour. Nearly half of all alcohol buyers (47%) still end up purchasing a duty free-exclusive product.
However, demand for exclusives has weakened over time, falling from 62% in 2022 to 47% in 2025, before edging up marginally to 48% in the first half of this year.
The same pattern is reflected in shoppers’ willingness to try something new. First-time purchases in the alcohol category have declined steadily, from 62% in 2022 to 55% in both 2025 and the first half of 2026, suggesting that alcohol shoppers are increasingly gravitating towards familiar, trusted brands rather than experimenting with new ones.
The regional picture reveals a clear divide in shopper behaviour. Africa & Middle East stands out as the strongest market for ‘quest for discovery’ behaviour, with nearly eight in ten (79%) alcohol shoppers making a first-time purchase in GTR, followed by the Americas at 72%. These two regions also lead in purchases of channel exclusives, with 54% of alcohol shoppers in Africa & Middle East selecting exclusives, closely followed by 53% in the Americas.
European alcohol shoppers, by contrast, are markedly more conservative in their purchases. Just half (50%) made a first-time alcohol purchase in GTR, while only 40% bought a duty free-exclusive – the lowest levels recorded across both behavioural criteria.
The Chinese pursuit of rarity and authenticity
The Chinese alcohol shopper is defined by a marked quest for exclusivity that shapes their distinctive purchasing pattern. Spirits shoppers, in particular, view exclusives and limited editions as an appealing feature of duty-free shopping, with nearly twice as many Chinese consumers (23%) drawn to rarities compared with alcohol buyers globally (11%).
This demand is undoubtedly driven by a strong preference for product authenticity, which appeals to 26% of Chinese alcohol shoppers versus 18% globally.
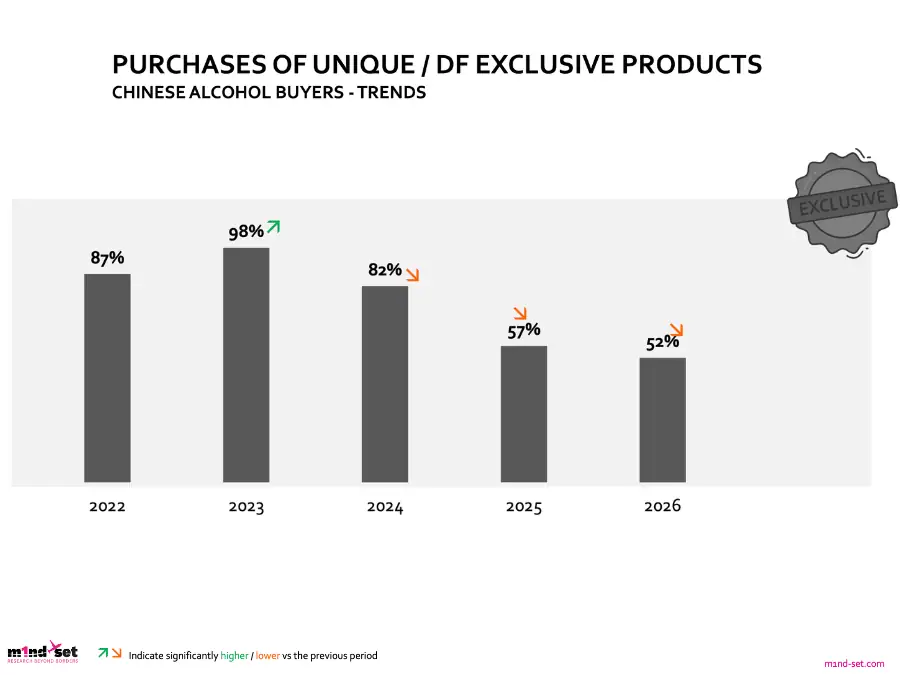
The strength of this exclusivity mindset was most evident in 2023, when an extraordinary 98% of Chinese alcohol shoppers purchased a channel-exclusive product – almost double the global average of 54% among alcohol buyers during the same period.
After the 2023 phenomenon saw almost every Chinese alcohol buyer seek out something unique in GTR, the appetite for exclusives remained robust in 2024 at 82%. But enthusiasm among Chinese alcohol buyers for exclusives appears to have settled at more moderate levels (57% in 2025 and 52% in the first half of 2026).
The same moderation is evident in first-time purchases. After reaching a high of 78% in 2022, the proportion of Chinese alcohol shoppers buying a product they hadn’t purchased before has declined steadily, falling to 67% in 2025 and 48% in the first half of this year – below the global average for alcohol shoppers.
However, Chinese travellers’ appetite for exclusivity remains particularly strong in some markets. Europe ranks among the weakest-performing regions globally for alcohol exclusives with just 40% of duty-free exclusives bought in its GTR channel over the 12 months from mid-2025 to mid-2026. Yet it has become a premier destination for Chinese alcohol connoisseurs seeking rare bottles.
Over the same 12-month period, 65% of Chinese alcohol shoppers travelling through Europe purchased a channel-exclusive, outperforming the global average for Chinese buyers (56%) during the same period.
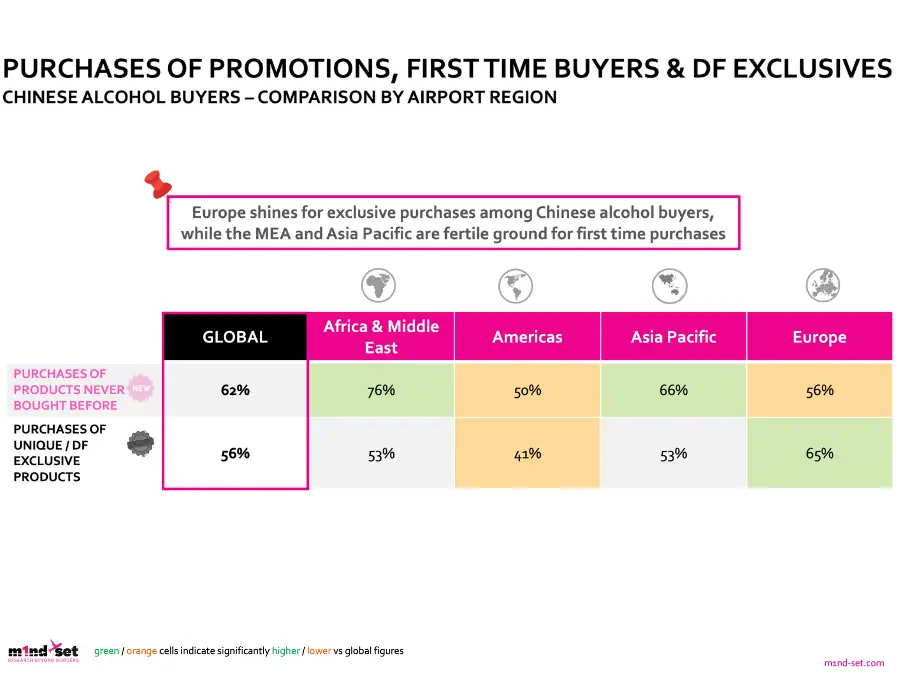
Retailers in Africa & Middle East emerge as the winners when it comes to first-time alcohol purchases made by Chinese shoppers. More than three-quarters (76%) of Chinese alcohol buyers purchased a spirits product in the region for the first time, well above the global average of 62%. Asia Pacific follows at 66%, highlighting the continued importance of regional travel hubs in driving product trial among Chinese consumers.
For brands and retailers, the winning formula for attracting and converting Chinese alcohol shoppers requires tapping into their deep-rooted appetite for authentic, high-status and regionally significant products. These values remain central to the Chinese traveller’s ongoing quest for distinctive and exceptional experiences in travel retail.
For a more detailed analysis of alcohol shopping behaviour, click here to contact m1nd-set directly.
Members-only intel
Keep reading this members-only article – and every one like it
- ✓All paywalled news and interviews
- ✓Category and market data
- ✓Monthly GDI magazine
- ✓Full archive + daily newsletter
Secure checkout · Cancel any time · Company invoices available
Already a member? Log in
See all plans, incl. 10-reader and corporate
Check if your company already pays for you Your company may already give you free access.
Corporate subscribers: AB InBev, Bacardi, Campari Group, Diageo, Moët Hennessy, Pernod Ricard, Proximo Spirits, Suntory Spirits Group, William Grant and Sons.
Activate company accessNot ready yet? Get the headlines free in our daily newsletter.
Sign up free