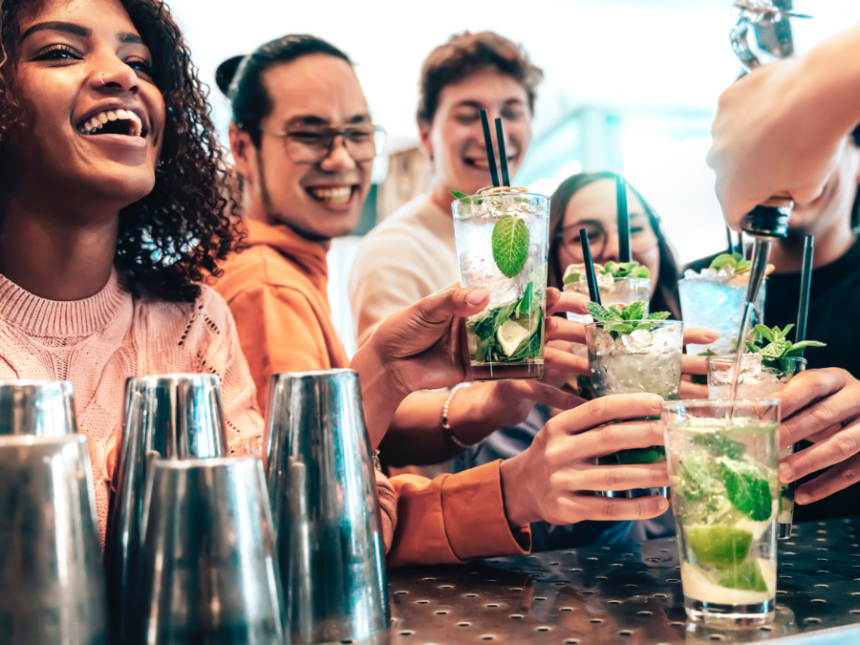
After years of disruption, the on-premise channel is showing signs of revival in key countries, such as China, Germany, Italy, Mexico, the UK and the US, driving a long-awaited note of optimism for the beverage alcohol industry.
The propensity to leave the home over-indexes for US Millennials in particular; as their circumstances start to improve, scotch whisky, liqueurs and sparkling wine are the biggest beneficiaries.
Latest data from IWSR’s ‘Bevtrac Wave 2 2024’, a longitudinal tracker of consumer behaviour for total beverage alcohol (TBA) across 15 key markets – Australia, Brazil, Canada, China, France, Germany, India, Italy, Japan, Mexico, South Africa, Spain, Taiwan, the UK and the US – shows a year-on-year rise in on-premise consumption incidence on the most recent drinking occasion in some markets.
Moderation is evident in both the on- and off-premise, however, consumers continue to drink more when they are out.
“The on-premise is a key driver of growth, and its slowdown, driven by price increases and changes in consumer behaviour, has hampered TBA as a whole,” says IWSR‘s senior insights manager for Bevtrac, Ivana Mitic. “IWSR’s latest Bevtrac data shows a growing revival in the the channel for some markets, offering a much-needed boost for the industry.
“As consumers return to bars and restaurants, we see a renewed focus on premium experiences and diversified offerings, laying the groundwork for future growth.”
The recovery of beverage alcohol continues at a cautious pace. Uncertainty among consumers, and the continued rise of moderation, has temporarily disconnected the link between rebounding real incomes and alcohol volumes and spend. Consumer confidence, however, is slowly recovering in the US, Europe and Latin America, and is generally stable elsewhere. In the first six months of this year, IWSR market data shows that overall TBA volumes have also registered growth in selected developing markets, such as Brail, India, Mexico and South Africa.
“The global beverage alcohol market is experiencing a period of profound change,” Mitic continues. “Moderation is becoming ingrained in consumer habits, while no-alcohol offerings and premium categories are gaining traction. Understanding these shifts and the impact to behaviour in the on- and off-premise is essential for adapting in an increasingly competitive market.”
Economic strains tighten alcohol budgets – emerging markets are a bright spot
While improving household incomes in regions such as North America and Europe have not yet translated into rising alcohol spending, emerging markets such as India (+4% volume change, H1 2024 versus ‘23), Brazil (+4%) and South Africa (+5%) are showing robust volumes increases in the first six months of this year.
Growth in India is supported by a confident urban middle class and a younger LDA cohort that continues to trial new categories. Brazil and South Africa, meanwhile, are benefiting from improving economic sentiment and a growing appetite for on-premise occasions.
Consumers opt to reduce consumption rather than abstain entirely
With the exceptions of China and India, moderation sentiment is evident in all markets; consumers in European markets are consistently most likely to claim they are cutting back on alcohol.
The rate of TBA non-consumption across the 15 key markets has been easing since April last year, especially in the US, China and India. In terms of moderation behaviours, Drinkers are reducing their intake rather than abstaining. Temporarily stopping drinking for a period of time remains a popular strategy, with the majority of consumers in India, South Africa and Latin America claiming to do so.
There has also been a shift from away from heavy drinking as ‘light drinkers’ – those with low frequency and/or intensity – become the biggest group in terms of consumption levels in Europe, North America and Asia Pacific.
No-alcohol momentum strengthens
Trial rates for no-alcohol products continue to rise: In the last six months, over a quarter of TBA drinkers have consumed no-alcohol beverages.
Consumption per person of no-alcohol products is on the rise across North America, India and China. Participation in North America has doubled compared to a year ago, aligning with strong volume growth in IWSR market data. Germany and Spain show the highest penetration rates for no-alcohol products (40%), while in the US, no-alcohol spirits are gaining traction.
Despite the momentum, the category remains price-sensitive. The recalled spend on no-alcohol products is trending negative, suggesting increased competition and down-trading among consumers.
Premiumisation persists despite challenges
Higher-income consumers continue to show resilience, even as economic pressures mount.
In spirits, premium-and-above categories, particularly single malt scotch whisky and cognac, are experiencing growth in India, for example, with typical per-bottle spend increasing by over 20% year-on-year.