
- Almost nine in ten (88%) of South Korean consumers visit the on-premise channel (+3pp vs the Asia-Pacific average)
- 61% of consumers in the country visit the channel weekly (+1pp vs the global average)
- Three-fifths (60%) are ‘likely’ or ‘very likely’ to purchase a drink for at-home consumption if they enjoyed it in a bar or restaurant
- Both spirits (-8.1%) and beer (-7.2%) have fallen in value in South Korea’s on-premise, but tequila (+0.3pp) and gin (+0.4pp) have grown
- Whisk(e)y accounts for just over 75% of the spirits sold in the country’s on-premise, a decline of 0.7pp year on year, with blended whisk(e)y down 0.9pp and single malt up 1pp
Culturally influential and teeming with potential, South Korea’s on-premise is in good health – 88% of Korean consumers typically visit the channel, up 2 percentage points (pp) versus a year ago and 3pp above the average of Asia-Pacific markets.
Frequency is also high, with 61% of users visiting weekly (1pp above the global average), according to NIQ ‘Opus’ and ‘Reach’ surveys. Spending is robust, too. The average monthly visitor spend is just under KRW255,000 (US$166), up 8pp year on year, with more than one in three consumers willing to trade up for a better-quality drink.
That said, the South Korean on-premise landscape is not without its challenges. Total visitation to bars, cafés and restaurants is down 8.1% compared with one year ago, 2.7pp below the Asia-Pacific average, and only 18% of consumers expect their visitation to increase over the next year.
The drop-off is, at least in part, likely driven by financial concerns stemming from economic instability and rising prices for everyday necessities (all trends being seen across numerous markets globally). Indeed, 30% of consumers report that their disposable income is, overall, worse than last year, compared with a 23% global average, and only 26% report a positive outlook versus 43% globally.
While these financial pressures are clearly affecting the willingness of Korea’s consumers to spend in the country’s on-premise, there are signs of gradual recovery. Overall visitation is up 2pp versus last year, with a more pronounced rebound in eating-out occasions, which have increased by 4pp year on year.
Diversity in drinks choices
With economic challenges influencing consumer behaviour, on-premise operators and brand owners must refine their channel-specific strategies to capture the opportunities presented by the industry’s positive trajectory, and remain competitive and profitable.
Looking first at category performance, spirits have dropped 7.9% in value. Beer is also down, falling 8.1% in volume and 7.2% in value. These two categories are performing less poorly in the off-premise. Both spirits and soju, for example, have lost just under 1% in volume, and spirits have even posted a slight gain in off-premise value.
Yet brands should not underestimate the role that the on-premise often plays in driving retail success.
In South Korea, 60% of consumers say they are ‘likely’ or ‘very likely’ to repurchase a drink for at-home consumption if they try and enjoy it in a bar or restaurant – a behaviour that’s strengthening, up 12pp year-on-year. Dismissing the on-premise simply because a product is currently performing better in shops, therefore, is far from a future-proof strategy.
Despite the overall slump of the spirits category, some emerging sub-categories are sustaining or growing their share of volume. Tequila, for example, comprises just 3.2% of the market in South Korea’s on-premise, but has grown 0.3pp year-on-year. Gin similarly makes up just 3.4% of the market, but has gone up even more, by 0.4pp.
The picture is more nuanced when it comes to whisk(e)y, so businesses needed to dig deeper into the data to understand how to manage this category effectively.
Whisk(e)y accounts for just over three-quarters of spirits sold in the country’s bars, cafés and restaurants. It is a rather significant share, but it is 0.7pp lower than last year. This is unlikely to indicate a loss of appeal across the entire category, though.
In fact, the decline is concentrated in the more popular blended whisk(e)y segment, (which makes up 87.1% of market volume and has fallen 0.9pp).
Meanwhile, single malt has grown by nearly 1pp to reach a notable 12.9%, making it a key area for businesses to focus on in the coming months.
Premium and mindful growth
The premium price segment has become central to South Korea’s on-premise, resonating most strongly with younger consumers: 25% of Gen Z order more premium or expensive options – 5pp higher than the average consumer – and Millennials follow a similar pattern at 20%.
Mindful drinking is also increasingly becoming a main focal point – 28% of consumers say they plan to choose healthier options, while 25% intend to drink less alcohol. This trend should not be interpreted as a threat to the alcohol industry; it just underscores the importance of having the right offerings available.
Stocking drinks perceived as healthier or less harmful, including a diverse range of low- & no-alcohol options, allows operators to cater to evolving preferences while maintaining engagement and loyalty.
The premiumisation trend can further support businesses in maximising health-driven trends, as both premiumisation and mindful drinking are primarily driven by younger users. To fully capitalise, then, businesses should focus on offering premium options that align with mindfulness preferences.
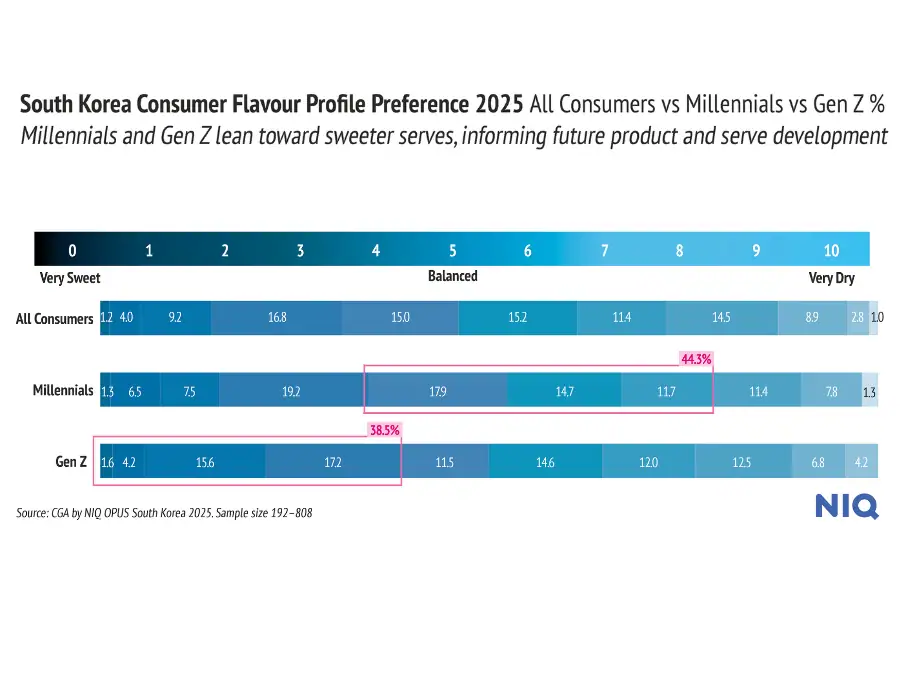
Research shows that Gen Z and Millennials are leaning toward sweeter serves and flavour profiles versus the average consumer (see chart below), so this should also be taken into consideration.
A food-led approach
Premiumisation is not only key to understanding what South Korean drinkers order, it also shapes their choice of venue and their visit frequency.
In fact, under economic pressure, more than three in four consumers would rather reduce their visit frequency than compromise on their choices when out, saving for fewer but higher-quality occasions. Capturing these drinkers at the right time and in the right place requires businesses to have a clear understanding of each channel and a well-defined strategy for engaging in them.
As noted earlier, in the current challenging economic climate, food-led venues are proving more resilient than wet-led bars. Indeed, lounge and cocktail bars have both seen a decline of just under 30pp in visit frequency versus 2025, whereas enduring favourites, such as traditional Korean eateries and BBQ, have experienced a much smaller scale of decrease of less than 10pp.
When looking at specific demographics, Korean BBQ has actually gained 7pp among Gen Z, meaning this is a channel to watch closely when targeting younger drinkers. For other food-led channels, the best approach is to prioritise a broader, more mainstream consumer base, focusing on the core portfolio where the strongest growth potential lies.
The faster recovery of food-led venues, however, does not mean opportunities are absent in the wet-led on-premise. In these types of outlets, businesses should concentrate on a smaller but higher-spending segment, particularly in bars, where the average spend is KRW33,245 ($22), and nightclubs, with KRW37,400 ($25). Once again, younger demographics over-index in these channels, spending more than the average consumer.
The opportunity in the South Korean on-premise is significant. With one outlet for every 97 people on average, it extends well beyond Seoul. Yet, the larger the scope of the venture, the more nuanced and targeted the strategy must be.
To fully succeed in this dynamic and crucial Asia Pacific market, every element of the on-premise experience should be carefully considered, with decisions guided by granular data on each outlet, audience, time of day and year, and category.
NIQ’s suite of research services, including OPM and Reach, provides brands and operators with an unrivalled, holistic view of South Korea’s on-premise sector. This enables businesses to address key questions around category, channel and occasion, and to optimise their sales and marketing strategies.
The company’s expert team can also deliver bespoke analyses, pinpointing tailored opportunities for individual brands and operators. Head here to explore how NIQ’s research can enhance your strategies and tolearn more about NIQ’s consumer insights for brands, operators and suppliers.
Alternatively, click here to email NIQ’s FMCG account development associate director in South Korea, Jaepil Sohn.
This article is available to Global Drinks Intel members only.
Click below for details on how to join the Global Drinks Intel community.
Already a member?
Log in here to read the article in full.
If you work for any of the following corporate subscribers to Global Drinks Intel, head here to activate your access.
- AB InBev
- Bacardi
- Campari Group
- Diageo
- Moët Hennessy
- Pernod Ricard
- Proximo Spirits
- Suntory Global Spirits
- William Grant & Sons