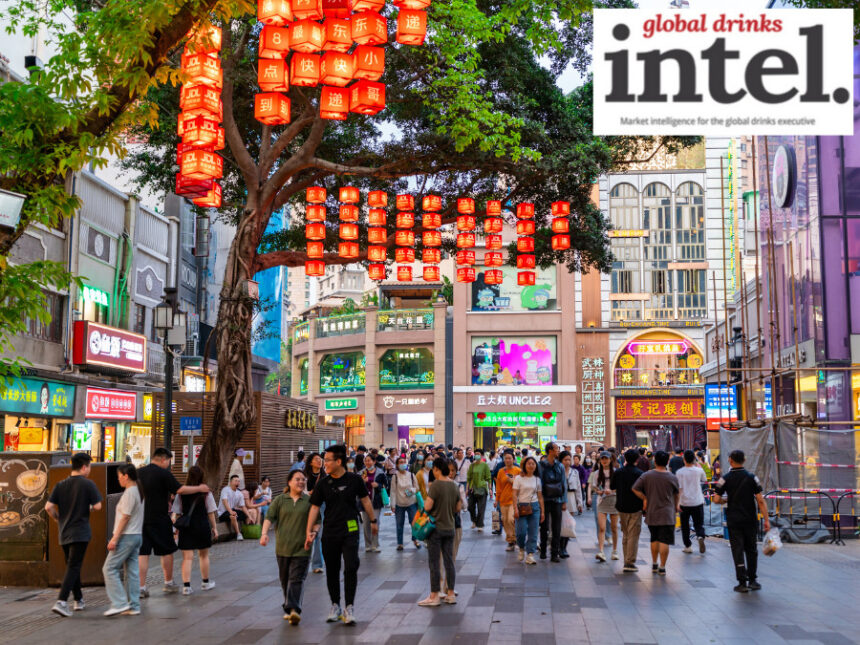
What’s happening in China? After years of pandemic lockdowns and disruptions, 2023 was meant to be the year when this enormous, and enormously promising, beverage alcohol market bounced back and began to fulfil its undoubted potential once again.
But no.
Last year, total beverage alcohol (TBA) volumes grew only marginally, according to IWSR data, as losses for spirits (-9%) and wine (-14%) were offset by gains for beer (+3%) and RTDs (+1%). Perhaps most shocking of all, scotch whisky volumes fell by 11% – the first decline for the segment in China since 2000.
In its recently-announced full-year results to the end of June, Diageo reported what were, on the surface, more positive numbers from the region: volumes in Greater China up by 14%, and sales rising 12%. But that growth came mainly from baijiu and the restocking of inventories in the first half of the year – a double-digit sales leap that merely reversed the declines of fiscal 2023. Meanwhile, the company’s scotch sales declined amid widespread downtrading.
“China’s beverage alcohol market is going through a period of normalisation following extended Covid-19 lockdowns,” says IWSR’s research director for Greater China, Shirley Zhu. “The industry is contending with destocking of high-end products, [and] consumer caution when it comes to spending amid a crisis in the property sector.”
Recovery, when it comes, will be slow, with positive momentum only likely to kick in from 2025, Zhu believes. “Premiumisation has been a strong driver for the market, but has slowed down for categories, with beer as an exception. Some categories saw downtrading as consumers were wary of spending.”
This downtrading phenomenon has been particularly noticeable, for the first time, among the lower-income cohort of middle-class Chinese, according to IWSR’s Bevtrac consumer research. It’s possible that this could be connected to a consumer perception that prices have been pushed up across premium spirits categories.
Losses for cognac and scotch as entertaining and gifting falls
As the last of the pandemic restrictions were lifted in early 2023, brand owner hopes were pinned on the reopening on-premise, but this took time to manifest and, says Zhu, the pattern of drinking occasions became more fragmented when it did.
“Many large nightclubs closed and will not reopen; new clubs and live music venues tend to be much smaller,” she explains. “Our market research team in China has reported less ordering of bottles of spirits or champagne with sparklers in the night-time scene. Younger LDA consumers were more likely to order beer buckets or drinks by the glass.”
The challenging macroeconomic backdrop led to a drop in high-end entertaining and gifting, with a serious negative impact on XO cognac and high-end scotch whisky. Beyond the notable slide for scotch last year, cognac’s 3% volume decline (-5% value) disguised double-digit losses for the segment’s prestige and prestige-plus price tiers. VSOP was flat (as was blended scotch), while VS enjoyed growth thanks to its more accessible pricing. “As the movement of products slowed, there were higher inventory levels by the end of the year, despite the efforts of brand owners and wholesalers to move stock,” reports Zhu.
One bright spot was the performance of imported white spirits, buoyed by the reopening on-premise. Albeit from a small base, gin volumes rose by 25% during 2023, with vodka up 24%, agave-based spirits surging 40% and white rum increasing by 44%.
The concern, however, is that these gains have been artificially boosted by the post-pandemic surge of customers into bars and nightclubs; Zhu warns that volume declines could easily follow in 2024 as the situation stabilises.
Still wine losses to continue
If anything, the mood is even darker when it comes to China’s wine market. While there is some optimism about the prospects for sparkling wine – despite a steep downturn in 2023 – still wine losses are expected to continue, with IWSR predicting a 2023-to-2028 volume CAGR of -2%.
“Total wine volumes will likely continue to decline in 2024, as demand remains weak,” says Zhu. “Recruiting younger LDA consumers to wine and generally broadening consumption occasions remain difficult.”
On the surface, the cancellation in March of China’s punitive import tariffs on Australian wine is a positive. The reality, however, is that it has merely added another country to compete for a shrinking pie of wine consumers in the market.
“The lift of the anti-dumping tariffs on Australian wine has given Australian wine a strong boost, but it’s at the expense of other wine origins, as consumption is not suddenly going to pick up,” explains Zhu.
“Still wine volumes are likely to remain at a low level for some time before consumers spend and explore again.”
Lower-priced sales are nosediving, leaving baijiu at a crossroads
IN spirits, baijiu continues to exert a stranglehold on consumption in China, but there are signs that the category has reached an inflection point, with lower-priced sales nosediving and brand owners looking to reinvent the drink for Millennial consumers.
According to IWSR data, baijiu accounts for 99% of spirits consumption by volume in the vast country, and 97% by value. The huge category spans an array of price points, from cheap, unbranded baijiu in rural locations to luxury brands consumed at high-end banquets – something illustrated by the fact that standard-and-below products make up 75% of category volumes, but only 29% of value.
“Baijiu is an integral part of the country’s culture,” says Zhu. “It’s the principal mealtime and banqueting drink, and pairs well with Sichuan and Hunan cuisine, which is gaining popularity across the rest of the country. The market is fragmented, with only a few brands enjoying truly national recognition and distribution.”
Tougher regulations and increased consumer education are eroding the market share of lower-priced products: Last year, according to IWSR, standard-and-below baijiu volumes declined by 11%, capping a CAGR loss of 12% for the 2018–23 period. IWSR forecasts continued declines, with a 2023–28 CAGR fall of 4%.
Prospects are rosier for premium-and-above price tiers, despite a challenging 2023 characterised by inventory pressures and destocking.
Zhu believes that competition from imported white spirits isn’t a huge factor here: high-end baijiu sales dwarf those of prestige imports, and the categories serve different occasions. “Western white spirits are usually drunk in bars and nightclubs, and often in mixed drinks/cocktails, whereas baijiu is traditionally drunk with meals,” she explains.
Nonetheless, brand owners face serious challenges. “Baijiu is in structural decline as its consumer base ages,” says Zhu. “To combat this, some producers are trying to reinvent baijiu for Millennials. They’re updating their marketing campaigns – for example, incorporating digital marketing campaigns that include cash discounts via QR codes – to attract younger LDA consumers and offer a lower barrier for product trial.”
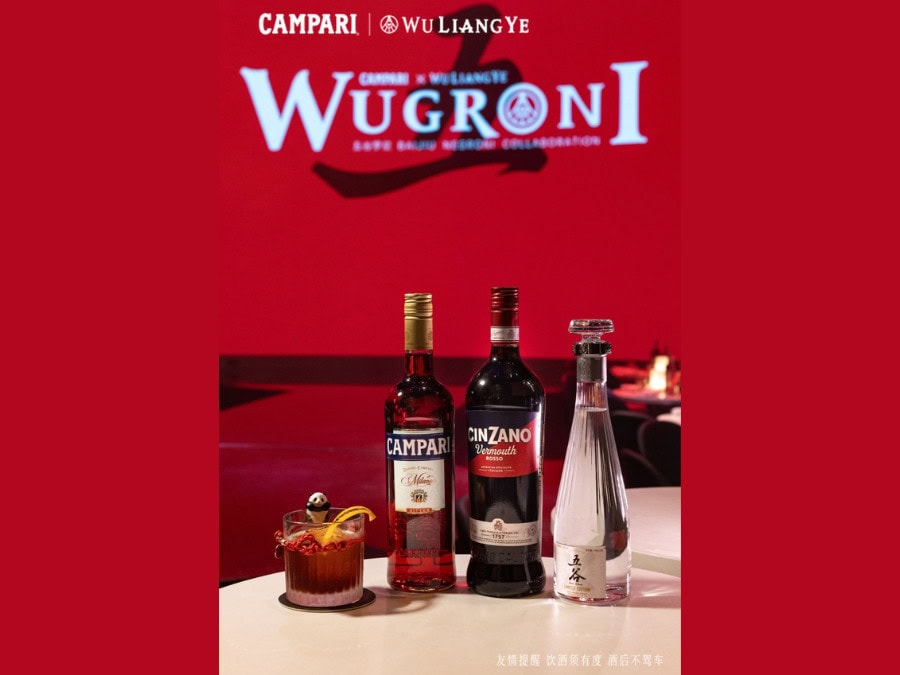
Meanwhile, others are diversifying into whisky or seeking partnerships in this area – Camus and Gujinggong being one example, reports Zhu. “Some producers have launched in other categories, such as ice cream and coffee,” she adds. “Some brand owners are expanding into new alcohol categories, such as Moutai into the RTD segment, and others into baijiu cocktails, such as Campari and Wuliangye’s wugroni (below).”
Longer term, market will remain ‘strong and resilient’
It all seems pretty depressing — and so it is, in the short term at least. This year, the process of normalisation continues in the Chinese market as consumers contend with a troubling macroeconomic picture and brand owners adjust their strategies and wait for inventories to unwind.
But, once this process is complete and the economic gloom begins to lift, the future looks considerably brighter, with IWSR forecasts predicting that by 2028, China will add US$14bn in incremental value.
“In the longer term, the Chinese market will remain strong and resilient,” Zhu says. “The number of upper-middle and high-income households is still growing, which will drive sustainable growth in the long term.
“Penetration of international spirits is still very low and has plenty of room for growth. Brewers are also tapping into the premiumisation trend, where lots of opportunity still exists.”