
It’s clear that across Europe, the cost of living is presenting a challenge for both on-premise operators and consumers. More so than their global counterparts, European operators are enduring exceptional challenges – nearly nine in ten have seen prices rise in food (89%), drink (89%) and energy (88%), while costs in other areas, such as front-of-house staff and insurance, have risen across the board as well.
As a result, over the last 12 months, businesses have raised menu prices by an average of 32% for drinks and 30% for food.
Increases like this are unavoidable in the current climate, but European operators remain conscious of the impact that such price hikes have on their customers. They are working hard to mitigate these cost increases to ensure they don’t become prohibitive, to minimise the risk of pricing some consumers out of the market.
European consumers are also facing cost challenges and there is no doubt that their finances have been squeezed. NIQ’s 2023 Consumer Outlook survey showed that nearly half of Europeans are worse off financially than they were a year ago, while just 17% are better off. Well over half are spending more on household expenses than they were only three months ago.
These numbers are higher than in most other parts of the world surveyed by CGA, reflecting the particularly severe impacts of inflation on the continent – and consumers anticipate this pressure continuing over the coming months too. That said, it’s clear the on-premise is still an important aspect of European consumers’ lives and they’re trying to navigate these financial concerns to ensure they’re still able to enjoy it.
Consumers in Europe are less likely to view restaurants and bars as places reserved for affordable treats – 56% compared with 63% globally – instead, they view the sector as the main forum for them to socialise with friends and family on a regular basis.
On-premise impressively resilient
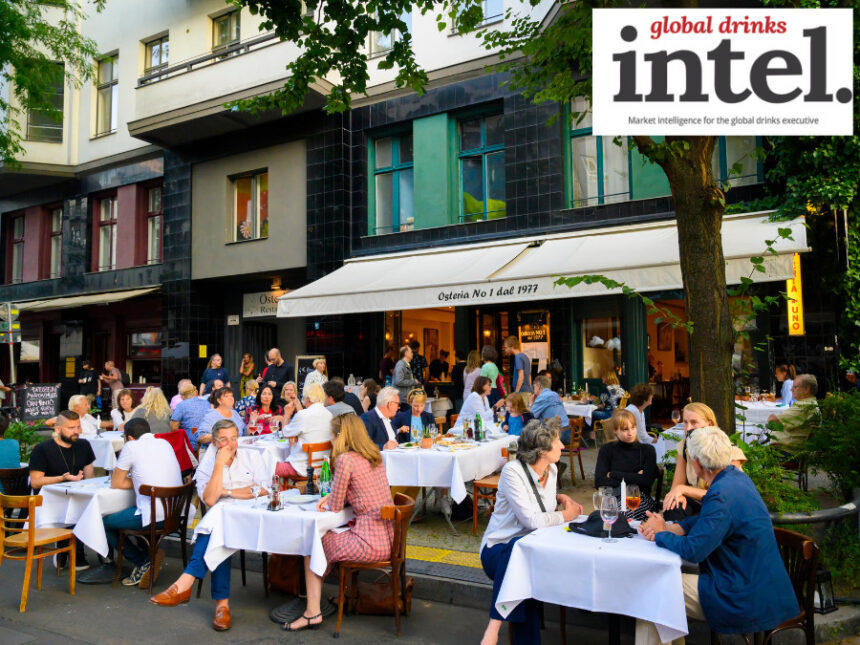
But it’s not all doom and gloom. Despite soaring costs, the on-premise has proved impressively robust across the major European countries. Four in five consumers still visit at least once every three months, while well over half do so weekly. Indeed, nearly a quarter (23%) of consumers are visiting hospitality venues more often than they did a year ago – more than the number who are visiting less (21%).
It’s clear, then, that consumers’ appetite for restaurants, pubs and bars is as strong as ever. In a scenario where they had a spare GBP50 (US$63), 22% would spend it on drinks or meals out – more than the number who would put it towards treats, holidays or bills. Three in five consumers say they would feel lost or disappointed if they were not able to eat and drink out.
In Europe, the on-premise is still the place where people go to relax, spend time with family and friends and treat themselves. Consumers do not want to lose access to this part of their life, even in difficult financial times.
The confidence of operators and investors remains solid as well. CGA’s UK Business Leaders’ Survey with Fourth showed more than half (54%) of leaders feel optimistic about prospects for their businesses over the next 12 months – well over double the number (22%) who feel pessimistic.
Of course, beneath these headline figures is a complex picture of on-premise engagement, which varies significantly from market to market, channel to channel and consumer group to consumer group. Understanding these nuances, and responding with locally focused, data-driven strategies, is crucial.
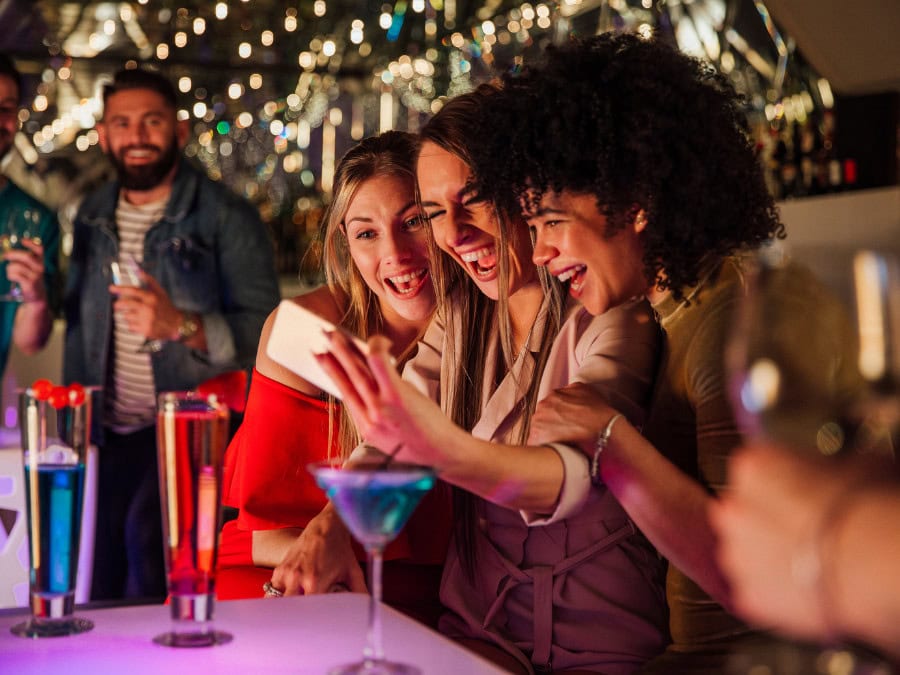
Engaging the consumers who visit more frequently…
Some of the best opportunities to win spend lie among the consumers who are most heavily engaged with the on-premise channel. CGA by NIQ’s Reach survey of consumers around the continent indicates that the current monthly visitation of those predicting their on-premise visits will increase is 30% more than average – which makes them a lucrative group to target.
The consumers planning to go out more tend to be younger and urban. Nearly half are aged 18 to 34, and 70% live in city or town centres. They significantly over-index for drinking cocktails and spirits including vodka, whisky/whiskey, gin, rum and tequila, and range and activations in these categories would help to attract and retain these valuable customers.
… as well as those consumers who visit less often
Some European consumers are being forced to tighten their spending in all areas of their lives, but even this group remains eager to go out when it can. More than half (55%) of those who say they have been severely impacted by the increased cost of living still visit the on-premise at least weekly.
However, they are now watching their spending closely, with 65% reporting that they stick to a specific amount they will spend on a night out. Good value is essential to these consumers and, despite huge cost pressures, operators will have to strive to maintain reasonable prices to avoid losing these guests. They may be focused on value, but this doesn’t mean cheap – it’s clear that European consumers also place a heavy emphasis on quality. They want to ensure that their hard-earned money is getting them high standards of food and drink.
While two in five consumers say they will go out less often because of the cost of living crisis, they want to maximise their experiences when they’re able to leave home and will prioritise their spend on quality. Put simply: consumers are prioritising quality and despite visiting less, will spend on premium when out in the on-premise.
Quality expectations aid ongoing premiumisation
Holiday market offers excellent opportunities for growth
A final significant opportunity for brand owners lies in the holiday market. CGA by NIQ’s Reach survey shows that European consumers have a stronger inclination to go out for drinks and food during their holidays than the global average.
This article is available to Global Drinks Intel members only.
Click below for details on how to join the Global Drinks Intel community.
Already a member?
Log in here to read the article in full.
If you work for any of the following corporate subscribers to Global Drinks Intel, head here to activate your access.
- AB InBev
- Bacardi
- Campari Group
- Diageo
- Moët Hennessy
- Pernod Ricard
- Proximo Spirits
- Suntory Global Spirits
- William Grant & Sons