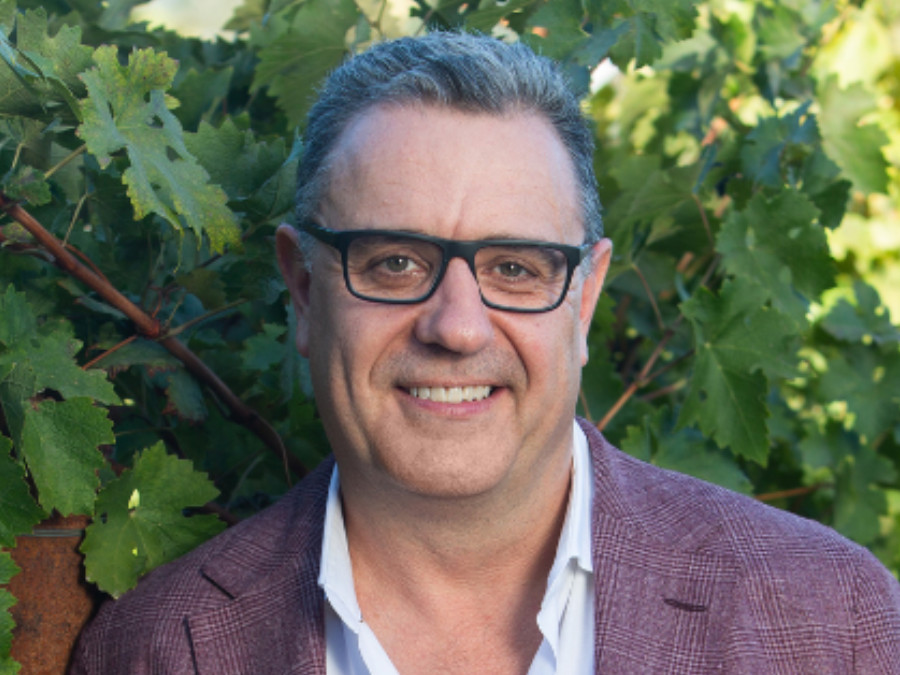
The occasion of this week’s fiscal full-year results announcement afforded Global Drinks Intel editor Olly Wehring the chance – for one last time – to speak to Treasury Wine Estates CEO Tim Ford, not only about the company’s latest figures but also about his five years at the helm, which draw to a close at the end of next month.
Presumably, you’re very happy with your final set of full-year figures, where sales rose by 6.1%?
The numbers for the year are the best we’ve produced. It’s a nice way to finish on all metrics. As a leadership team, we feel pretty happy with all the progress we’ve made and the numbers we’ve delivered through the ups and downs – and there have been plenty of both – over the last five years.
Does the continued weakness of the group’s lower-priced brands leave a bitter taste in the mouth?
We did try to sell them. We would have liked to have achieved that, but I’m pretty comfortable that we made the right decision versus what options we had on the table.
Today, 85% of the group’s earnings are from luxury wine – We’d love that to be north of 90%, of course, but it’ll get there pretty quickly just by their natural course.
The last thing I wanted to achieve was to get the separation of the business right with our three new divisions, where we can let those luxury portfolios flourish and the premium business [renamed Treasury Collective] can get some stability. I think we’re set up well and I’m comfortable that I’m handing Sam [Fischer, who starts as CEO on 1 October] a good team and a good business to take forward.
What was the trigger for you to decide to step down?
At the end of each fiscal year, I sit back and decide in my own mind if I have the drive and motivation, and whether I believe I can continue to add value for another two years – it’s always a two-year cycle in these sorts of roles.
When I did a fast-forward over the next two years and what we’ve got to achieve as a business – we’re very much moving into an execution phase – I felt like it was the right time. The business needs to be in a position where a change that’s always going to be a little disruptive will be its least disruptive. I felt like now was the right time for that.
How long is the ideal tenure for a CEO?
Every situation is slightly different, but I think five to six years is a reasonable time frame for a leader of any organisation. You get to the point where you look at what the business needs from a leader going forward and whether you can continue to take it forward.
Here at Treasury, we’ve probably been through more than five years’ worth of experiences over the last five years. We’ve crammed closer to seven or eight years into that time! I feel good about that, but I feel like it’s the right time.
Is the role of CEO generally somewhat overstated when it comes to leading a company?
The way I describe it is that you run the company and not the business. The company is very much an external lens, be that investors, media or governments – managing that side of it is a big part of the job.
A CEO’s role is to drive strategy in terms of the organisation of the business. I say to my team: This is the highway we’re going down, you pick the lane. As long as we’re on the right highway, then I’m happy.
A CEO also sets the tone and has a huge responsibility for the culture and standards in the organisation. When I was chief operating officer before this role, I was in the business everyday, I knew every number and I was driving what I would call the enterprise decision making, not the business unit decision making.
Is it better to move internally into the position of CEO, as you did, or to have an outsider come in?
Both and neither! It depends on the circumstances and our circumstances are a good example. When my predecessor, Michael Clarke [who was CEO from 2014 to mid-2020], came in, we were a typical wine business – agricultural-led and caught up in the emotion of making wine. Mike brought a really sharp, brand-led, FMCG-led urgency to our business that we needed.
At that point in time, an external hire who had no background in our industry but knew how to reshape organisations and chase down growth was perfect.
Then, when I took over [in July 2020] , it was the right time for an internal recruit; we had to continue to drive an agenda that was already in place and that I’d been part of with Mike. It worked well because I had the relationships in the business – I was a known quantity. This was also at the height of Covid, when we had to run the business on video for 18 months. For someone new to the business to do that would have been exceedingly challenging for them.
It’s horses for courses, but I hope a lot of companies look at an outsider coming in as good, because that’ll be the next thing I’ll probably do – I’m now talking against myself here!
Your successor is an outsider [Sam Fischer is CEO of Kirin Group’s Lion beer division and a former regional president at Diageo].
The board has made a good decision here: Sam’s Diageo background brings what I think will elevate us for the next three to five years – brand-led, global brands and building the Asia and US businesses continuously.
Sam’s current position is in a volume-focused alcohol category – Is that a concern?
What Sam brings to this job is a bit of what he’s done in the last three years, but more what he’s done in the 17 years before that with Diageo. He’s got deep knowledge of and experience in Asia markets. Having been the CEO of a company for the last three years adds to that toolkit, so he’s well set up to be successful.
That said, if you haven’t done it before, you’re never ready to be the CEO of a public company – you’ve just got to learn it as you go.
What’s your prognosis for the wine category, moving forward?
Luxury wine – that’s wine at AUD30-plus (US$19.60) – is growing in every market around the world, has done for a number of years and will do for a number of years ahead. That’s where consumers are going; they’re drinking less wine but they’re drinking better, in terms of the price.
The lower price points – certainly up to AUD15 – are becoming commoditised because the margin structures are smaller and younger consumers gravitate towards brands, not categories. Brands are more important in their minds these days, so if you don’t have the margin to invest in A&P and building those brands, then they’ll become commoditised. That’s structural.
It’s still a huge category, but if you’re a business whose centre of gravity is at that bottom end, then every dollar matters as opposed to having the margin with which to build a brand. So, I’m very bullish about the luxury wine category.
What advice would you give to the category?
It’s about value, not volume. You’ve got to be innovating and providing value to the consumer. Speaking of which, the consumer has to be front and centre of all of your decision-making. Historically, wine has had a tendency to market to itself – while we are consumers, at the end of the day, we’re a very small part of the consumer segment.
This is where the RTD category and a lot of spirits brands are doing fabulously well – they’re tailoring to the consumer. I always use 19 Crimes as an example when I come to this; a brand our winemakers dislike, but our consumers love it. It doesn’t have a history, it doesn’t have terroir, but it’s gone from being very small to being very big. That’s the kind of proposition that wine companies need to continue to build.
Do you have any tips on attracting new consumers, particularly younger ones?
This is not a new challenge, even though it gets a lot of airplay these days. My generation didn’t drink wine until we were at least 25 either! No one drinks much wine in nightclubs anyway, but when they start moving to sit-down meal occasions, then they’re doing it. They’re just drinking less of it and at higher prices than my generation did.
More and more these days, it’s about building brands. The wine category is very confusing and hard to explain, and every consumer wants to bring a wine to a dinner party that they’ve got an anecdote about. The trust in brands and the story behind those brands is what gives people the opportunity to do so. That, in my humble opinion, is the really important part.
What does your legacy to Treasury look like?
I really dislike that term, but I’ll give it a go! Five years ago, less than 50% of our earnings came from luxury wine. Today, it’s 85%. We’ve really shifted our entire business up the value chain to where the consumer’s going. That will set us up for the next decade. I feel really good about that.
In terms of what I would have liked to add that I haven’t got, share price growth would be good. It’s a source of immense frustration, when I look at our earnings up 60% and our margins up by seven or eight points over that period of time, yet we haven’t created shareholder value under my tenure.
Ultimately, as the CEO of a public company, it’s about the stock price. Unfortunately, that’s not going to be part of my story, but I absolutely believe it will come.
What are you going to be doing on the morning of 1 October?
I’ve already got a golf tee booking at 9:06 AM!
I’d be surprised if I ended up taking another role in wine, purely because this is the best job in the industry that I’ve had the opportunity to do. I’d find it very difficult to find something that would give me the satisfaction that this one has.
This article is available to Global Drinks Intel members only.
Click below for details on how to join the Global Drinks Intel community.
Already a member?
Log in here to read the article in full.
If you work for any of the following corporate subscribers to Global Drinks Intel, head here to activate your access.
- AB InBev
- Bacardi
- Campari Group
- Diageo
- Moët Hennessy
- Pernod Ricard
- Proximo Spirits
- Suntory Global Spirits
- William Grant & Sons