
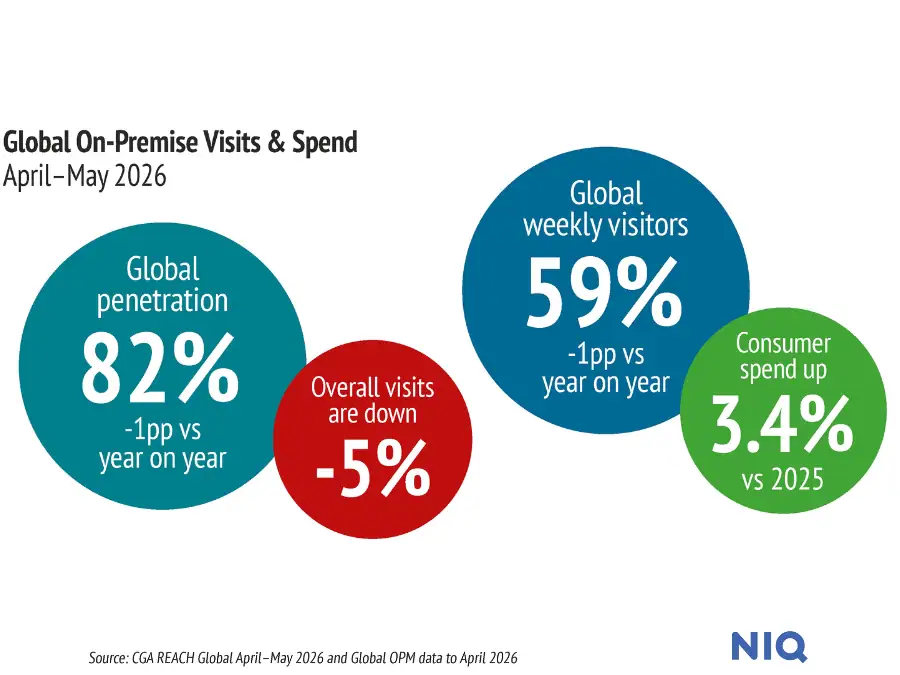
- On-premise visits are falling – Total visits are down 5%, with beer and spirits volumes also declining across major markets
- Consumers still want to go out, with three in five saying they visit the on-premise weekly
- Fewer visits, higher spend – On-premise users are prioritising higher-value experiences that feel worth the expense
- Moderation is reshaping drinking occasions – Consumers want to manage their drinking and enjoy the full social experience of going out
- Premium is now about the experience – Service, atmosphere and execution all count, not just what’s in the glass
Around the world, the on-premise is seeing a major shift in consumer behaviour, with visits and volumes falling. According to new research from NIQ, however, demand for meaningful, higher-value experiences remains alive and well.
The company’s ‘REACH 2026’ study, which analyses consumer habits and needs across 46 countries, found that in the 12 months to the end of April, total on-premise visits fell by 5% year on year, contributing to similar declines in beer and spirits volumes across major markets.
The findings point to a challenging outlook for venues, with global economic pressures on consumers and businesses compounded by local market factors. But the research also suggests that the sector retains significant underlying potential.
While on-premise volumes fell significantly in the 12-month period, the value of sales actually rose. Consumers might be visiting less, but they are maximising their spend when they do go out, and this is creating higher-value and more intentional occasions.
The traditional on-premise model, based on frequent visits, is evolving.
Consumers still want to go out
Despite the visitation drop-off, the appetite for eating and drinking out remains strong.
About three in five consumers visit the on-premise every week, with younger generations particularly engaged. Gen Z consumers are 11 percentage points more likely than average to visit weekly. Meanwhile, 57% of consumers say they would feel lost or disappointed if they could no longer go out, while more than one expect to visit venues more often over the next three months. Just 14% expect to go out less.
The recent FIFA World Cup showed that consumers will turn out in force for major shared occasions, filling pubs and bars around the globe. The challenge, therefore, appears to be less about consumers losing their appetite for socialising and more about giving them a compelling reason to head to an on-premise venue.
This desire to go out combined with the drop in on-premise volumes paints a picture of an on-premise with strong underlying potential, but one that is no longer driven by frequent visits.
Fewer occasions, higher spend
With consumers going out less frequently, growth increasingly depends on spend. On-premise visitors are concentrating their spending on fewer, higher-value and more intentional experiences, prioritising moments that feel special, create lasting memories and justify the expense.
This creates an opportunity for channel operators and brand owners to extend their presence beyond traditional on-premise settings and tap into occasions where consumers are most engaged.
To succeed, however, businesses cannot wait for the old on-premise model to return. Instead, they must adapt to a new definition of going out – one in which the quality and relevance of the experience matter more than frequency.
Moderation creates opportunity
This process of adaptation must also reflect a key shift in the consumer’s relationship with alcohol: mindful consumption. More than three in five on-premise users are now actively managing their alcohol intake.
It is crucial to understand that mindful drinking is not necessarily a negative for the on-premise channel. Instead, it should be viewed as an occasion multiplier.
The shift in behaviour is nuanced: choosing no- & low-alcohol options is rarely a binary decision. Many drinkers who moderate their alcohol intake still choose full-strength serves for high-energy or celebratory occasions, while opting for mid-strength, lower-ABV or alcohol-free alternatives at more relaxed or everyday moments.
The trend, therefore, is not simply about drinking less. Rather, moderation is changing how consumers engage with alcohol. Drinkers want to pace themselves so they can stay out longer and make the most of the occasions they choose to spend in the on-premise.
For brands and operators, this makes the ability to offer a broader range of options increasingly vital. Winning the initial order is always important, but the real growth opportunity lies in securing the ‘another one’ moment.
This can be achieved by offering compelling mid-strength and lower-ABV drinks that allow consumers to pace themselves without stepping away from the occasion, or by integrating alcohol-free options that can be alternated with full-strength serves.
Whatever the approach, success depends on recognising how today’s consumer wants to manage their drinking while still enjoying the full social experience of going out.
A new premium
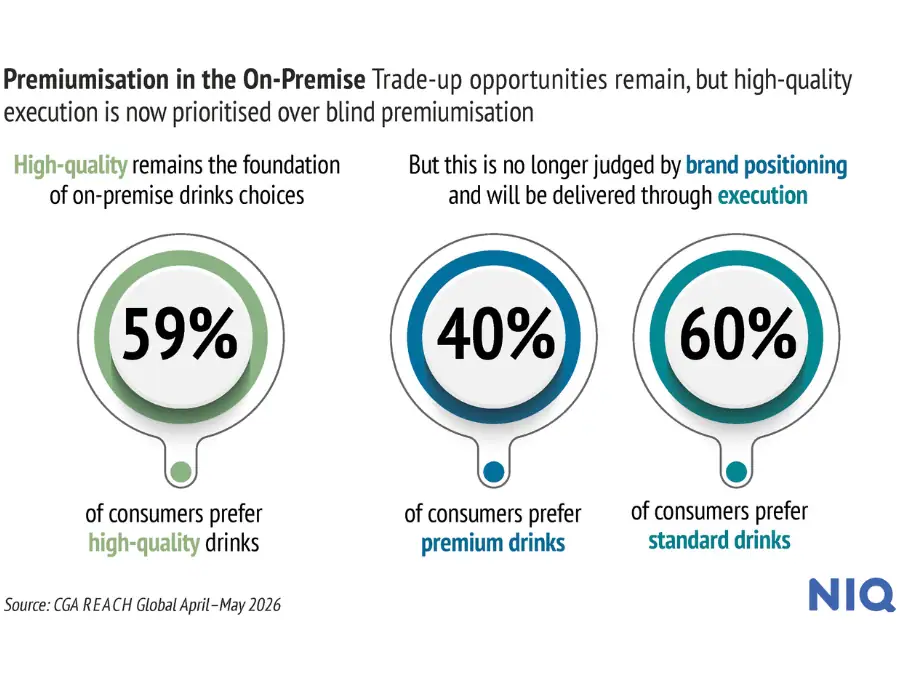
The consumer also continues to trade up despite pressure on disposable incomes. More than half will pay more for a better-quality drink. The key question here is what the consumer now means by ‘higher quality’.
While the idea of premiumisation interpreted as ‘less but better’ remains relevant, the trend has become more complex as the consumer grows selective about discretionary spending.
Essentially, quality and premium are no longer defined solely by what’s in the glass: the overall drinking experience is now just as important as the product itself.
While perceptions of value are inevitably personal, service, atmosphere and execution all play a significant role in defining them. Premium is no longer simply a product attribute – it’s the combination of an exceptional drink and an experience that the venue delivers in the moment. A premium drink, therefore, needs to be supported by an experience that makes the additional spend feel worthwhile.
For brands and operators, this means that delivering a high-quality product is only part of the equation. Flawless execution, strong service and memorable experiences can all help justify a higher price and encourage consumers to trade up.
Simplicity drives choice
Making the consumer journey easier is another opportunity identified by NIQ’s ‘REACH 2026’ study. When simplifying their drinks choices, two-thirds of consumers favour simpler and more accessible options, while nearly three-quarters prefer beverages they perceive as palatable and easy to drink.
This does not mean consumers have lost their appetite for innovation or complex serves. More unusual serves remain particularly relevant among higher spenders. Instead, the opportunity lies in making the journey to the drink simpler. Even complex or innovative serves need to be easy to understand and order.
Trust plays a role in the process too. On-premise users are more likely to choose drinks they know because of their quality, consistency or reputation. Building and maintaining that trust will be a key competitive advantage for both brands and suppliers.
If a drink is inconsistent between venues, difficult to identify or fails to deliver the expected quality, that trust can quickly be lost. The challenge is to deliver serves that feel simple and accessible while retaining the premium qualities that consumers value.
A new on-premise reality
NIQ’s ‘Reach 2026’ report signals a permanent transformation in the on-premise landscape. While consumer habits have fundamentally shifted, channel operators and brand owners can no longer rely on frequent venue visits to drive growth.
Instead, success requires a sharp focus on consumer motivation – identifying what justifies the expense of a night out while delivering on rising expectations around moderation, premiumisation and simplicity.
To grow both value and volume, businesses need to adapt to this new reality and make every occasion count.
NIQ’s ‘Reach’ survey illuminates eating and drinking behaviours, offering valuable in-market insights and benchmarking for targeted consumer outreach. Head here to explore how NIQ’s research can enhance your strategies and learn more about NIQ’s consumer insights, or click here to email NIQ‘s global on-premise insights leader, Graeme Loudon.