In the US, Circana, which measures retail performance across grocery, convenience and multi-outlet stores, has been watching closely as 2025 shapes up to be unfavourable, as high hopes for summer sales have left many in the alcohol industry feeling the burn.
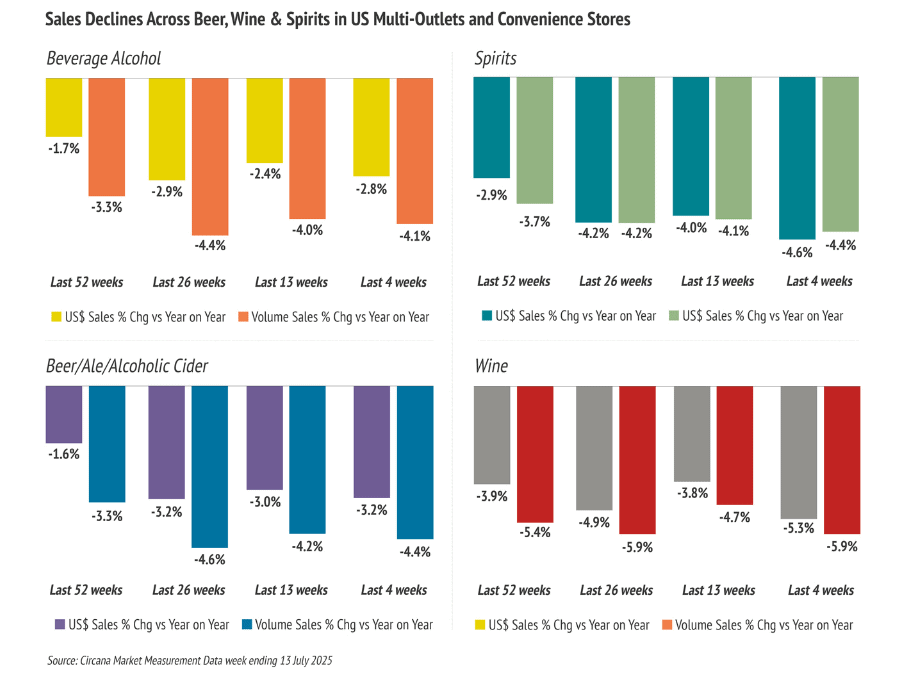
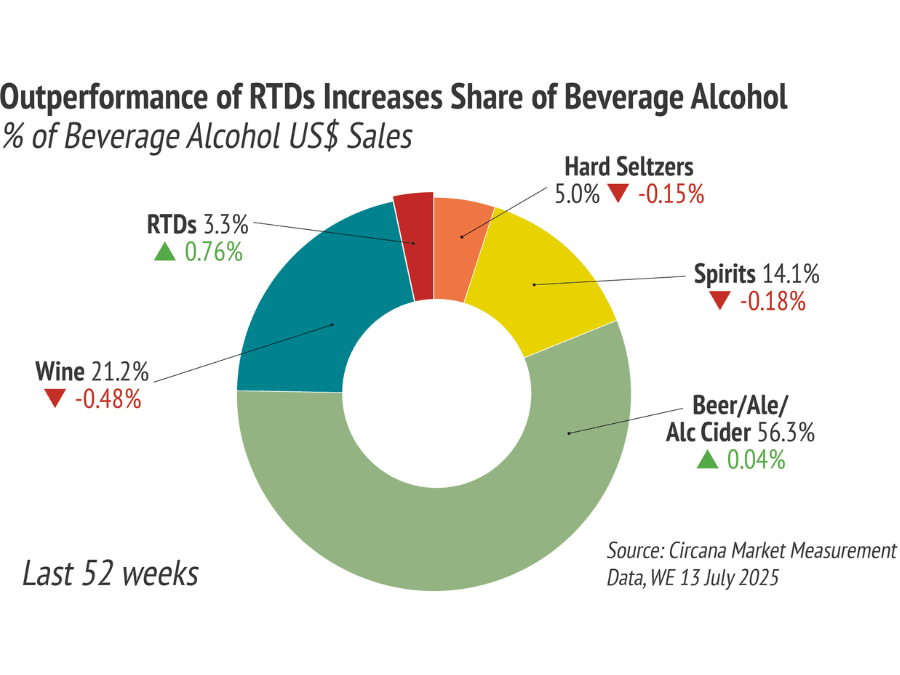
For the 52 weeks to 20 July, total beverage alcohol sales in the country were down 3.3% in volume and 1.7% in value. All major categories are facing declines, with numbers expected to drop even further in the full-year 2025.
Take a year of uncommon weather patterns and overlay macroeconomic concerns, consumer prioritisation of health and wellness, generational moderation, weight loss drugs and the continued unwinding of Covid-19 pandemic trends, and what you have is a perfect storm of factors that are making some wonder if 2025 is setting the stage for what is to come.
The weather has always been a controversial topic – some view it as an excuse masking larger trends at play. But, uncommon snow early this year in the southern US (where many northern consumers take respite over the winter months), followed by rainstorms in spring in the mid-west region and extreme heat in the south at the beginning of the summer, threw seasonal patterns off.
This impacted Memorial Day in May, viewed by many Americans as the unofficial start to summer, thwarting outdoor barbecue and picnic occasions that typically boost alcohol sales.
The industry quickly turned to hopes of explosive Fourth of July holiday sales, but the holiday failed to deliver broad sweeping growth across all beverage alcohol categories.
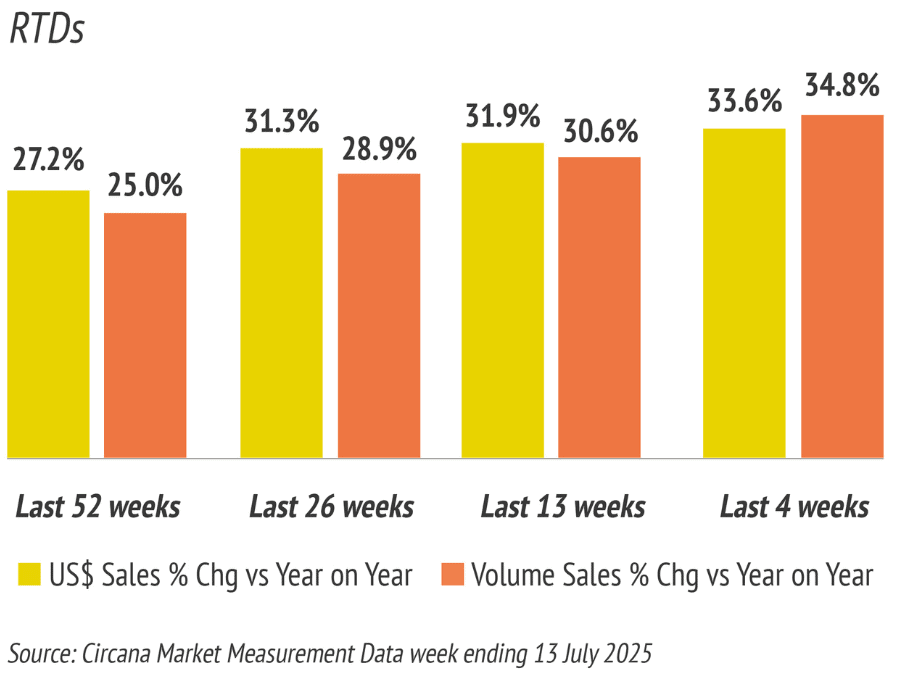
Pockets of solid growth were evident, especially within the popular ready-to-drink (RTD) canned cocktail segment, which showed double-digit growth, up nearly 35% in both volume and value across June and July.
Michelob, Busch Light & Pacifico standouts as beer struggles
Over the past year in the US, beer is down 3.3% in volume and 1.6% in value, with trends worsening over the summer. The category is dominated by the super-premium sub-category, with AB InBev’s Michelob Ultra proving to be one of the major driving brands.
Michelob is not only capitalising on the strength of top-selling lower-calorie, lower-carbohydrate Ultra, the brand is also leaning into the no/low space with Michelob Ultra Zero. Launched in January, the 0% ABV extension has increased momentum for the brand, satisfying consumers who are choosing non-alcoholic beverages either to supplement alcohol occasions or because they want to abstain from alcohol completely.
AB InBev’s Busch Light has also been connecting with consumer need states at a value price point, but with the added twist of a limited-edition apple flavour. First launched in 2020 but discontinued two years later, Busch Light Apple returned to retail shelves in May after consumer lobbying. The innovation has dramatically lifted sales to further enhance the brand’s positioning within the competitive top ten beer brands ranking.
The power of Constellation Brands’ Mexican import, Pacifico, is hard to ignore. Although the brand has yet to crack the top ten, it has grown by double digits year-on-year in the US, bucking negative trends faced by the overall category. Pacifico started as a west coast brand, popular in California, but has broadened its appeal across the US, becoming a workhorse across Constellation’s beer portfolio in the country, which also includes top-performing Modelo and Corona.
Another standout for beer has been Mark Anthony’s Mike’s Harder brand – actually a flavoured malt beverage (FMB), although categorised here under ‘beer’ – which continues to deliver consistent growth with a higher-ABV offering to challenge the rise of spirit-based canned cocktails.
Traditional hard seltzers have seen contraction over the past few years, down 7.5% in volume during the last 52 weeks to mid-July.
RTDs retain strong growth as hard seltzers decline in US multi-outlet and convenience stores
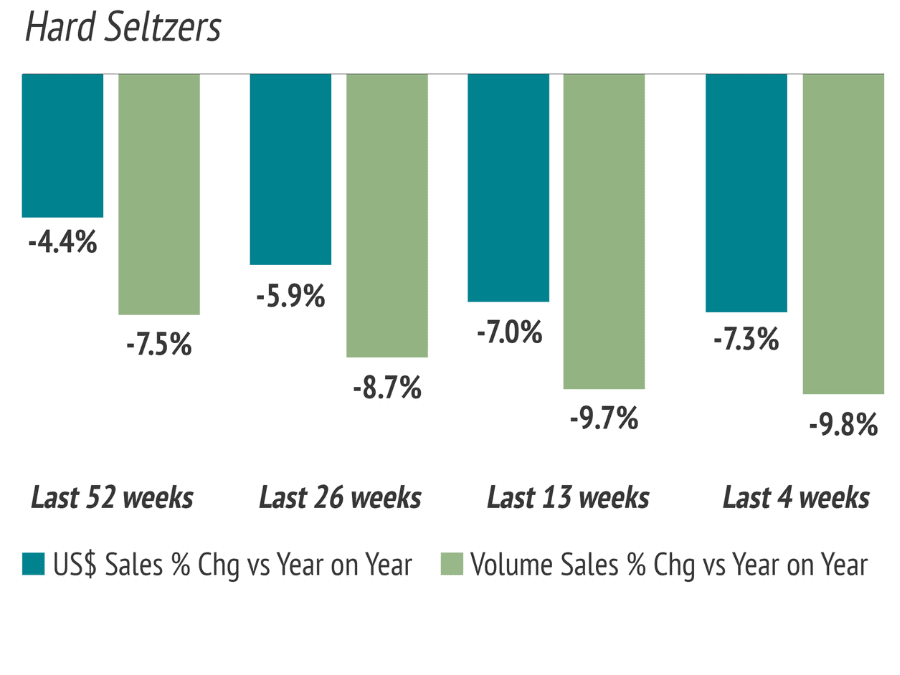
While the beer category began the year softer than anticipated, positive signs emerged in early August, which hopefully can translate to a more positive second half of the year and Labor Day holiday (1 September). Then, all eyes have turned to the start of the American football season in early September – a big deal for beer brands.
Spirits-based canned cocktails now driving category
The spirits category has slowed dramatically after a 20-year surge in popularity and is now being driven by canned cocktails. While Tito’s Handmade Vodka often leads in overall volume, Gallo’s successful spirit-based RTD High Noon accelerated beyond Tito’s during the Fourth of July, propelling it to the top position.
Other RTD cocktail brands, such as BuzzBallz (acquired by Sazerac Co last year) and BeatBox, also greatly outperformed key holiday occasions, showing strong consumer demand for flavour and convenience. These brands had astonishing triple-digit growth comps in 2024 and remain within spirits’ top ten, challenging traditional category leaders, such as Crown Royal, Jack Daniel’s, Jose Cuervo and Smirnoff.
Two brands, in particular, have been riding the wave of the fast-growing RTD vodka and tea segment of late. Boston Beer Co’s Sun Cruiser and Stateside Vodka’s Surfside saw explosive growth in 2025, accelerating to bcome top 25 brands across total spirits. And, at consistent triple-digit growth, it’s likely that both will crack top 15 status by the end of the year.
Most major spirits brand owners have entered the RTD segment to balance portfolio slowdown across other areas. Without question, US consumers continue to be attracted to RTD innovation from known brands, as well as new ones.
In comparison to a year ago, consumers not only spent more on RTDs, but also bought more frequently. SInce 2018, the segment has tripled and Circana forecasts it will reach nearly $11bn by year-end. Spirits-based canned cocktails, then, are providing a bright spot in an otherwise gloomy forecast for beverage alcohol.
Josh and Decoy bright spots as wine continues decline
The wine category continues to be the laggard within alcohol in the US, dropping 5.4% in volume and 3.9% in value over the last 52 weeks. The age-old adage that ‘brands drive categories’ has a kernel of truth, but even consistent outperformers across wine cannot make up for the precipitous drop in consumption as younger consumers gravitate to RTDs.
Josh, owned by Deutsch Family Wine & Spirits, remains wine’s growth leader, with bursts of outperformance during key holidays. The brand, which has a cultural cachet across social media, has at times challenged Gallo’s Barefoot, which holds the top volume position. La Marca Prosecco (also owned by Gallo) has also shown strength within the sparkling wine segment outside of celebratory occasions, consistently delivering gains versus the year prior.
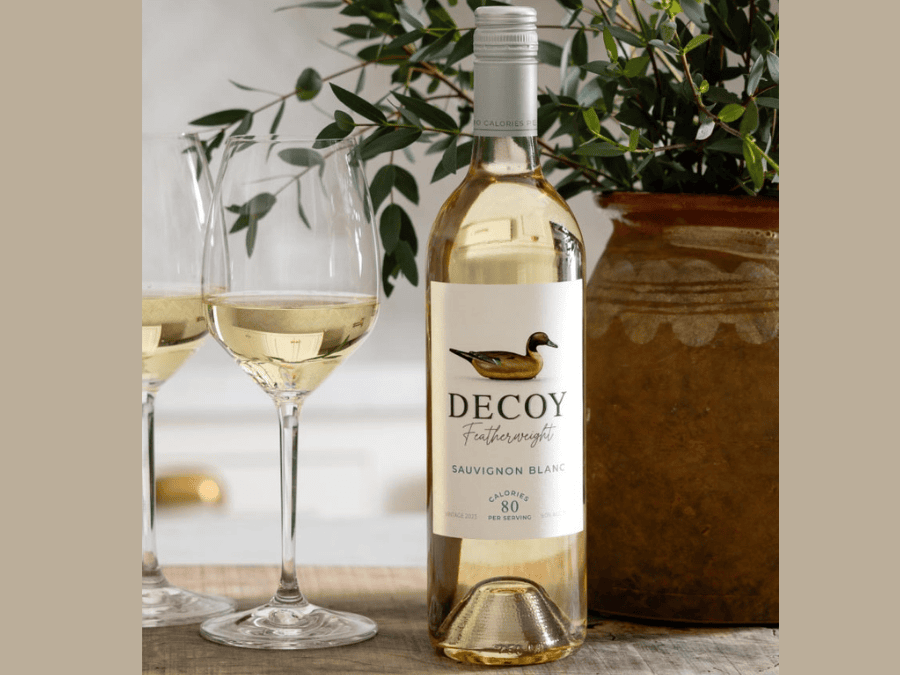
One wine brand to watch is Decoy (below), owned by The Duckhorn Portfolio, which has delivered double-digit growth in the first half of 2025 and is on pace to continue the momentum through year-end. As a subcategory, boxed wine remains appealing to consumers with brands such as Bota (Delicato Family Wines) and Black Box (Gallo) capitalising on the value-for-money trend that is emerging, as uncertainty around the US economy continues.
Adult non-alc makes inroads
Even though adult non-alcoholic (ANA) products have just a 5% share of total beverage alcohol within Circana-tracked retail channels, the segment has undeniable momentum. Outside of RTDs, ANA is one of the few subcategories that is consistently growing and increasing in relevance.
Appealing to a wide demographic of Americans focused on health and better living, ANA products have found a place among typical alcohol occasions. In recent years, the large US retailer Total Wine & More has doubled its shelf space to accommodate more ANA brands.
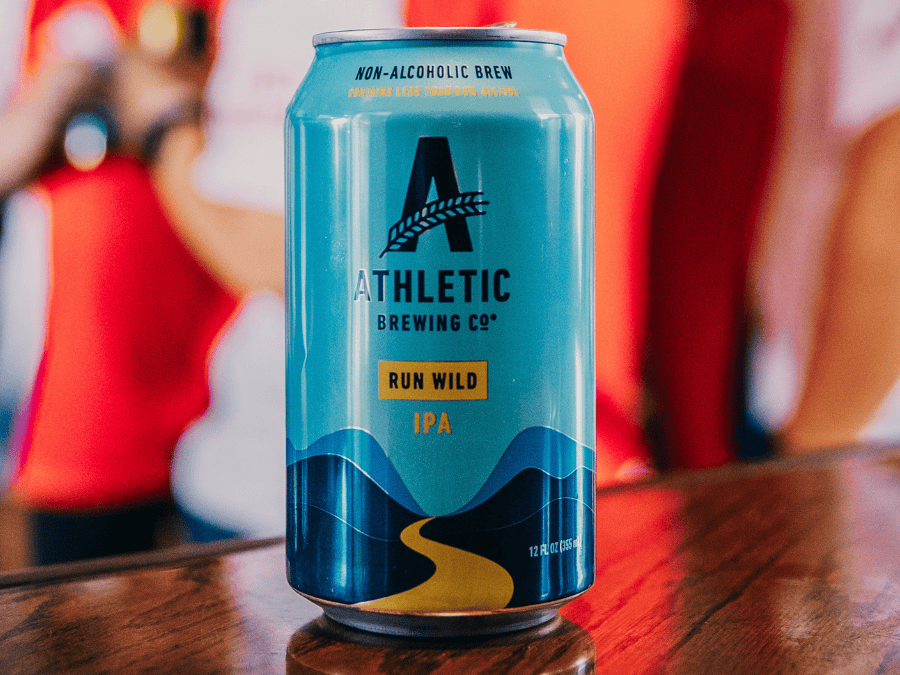
Led predominantly by zero-proof beer brands, including Heineken 0.0, Guinness 0.0 and Athletic (below), the ANA category is taking shelf space across the country’s off-premise channel to meet growing demand. While non-alcoholic wine and spirits remain concentrated to a few brands, the beer category has seen increased innovation from name brands, craft brewers and even celebrity-backed options, such as Spider-Man actor Tom Holland’s Bero.
A watershed year?
2025 may be a year of reckoning for the US beverage alcohol industry. Data from the retail channel, which accounts for roughly 80% of the country’s alcohol sales, points to an overall downturn. However, certain brands and subcategories are bucking the trend, suggesting a shift in how – and what – consumers are drinking.
While many analysts have focused on a potential end to premiumisation due to inflation and negative consumer sentiment around the US economy, most higher-priced products have proven resilient.
Consumers are still drinking, perhaps at a more moderate and price-aware pace than in the last five years, and demand for out-of-home experiences is still paramount. As Americans travel for end-of-summer vacations, there are hopes this may provide a much-needed boost for beverage alcohol – weather permitting.
Scott Scanlon is the executive VP for beverage alcohol at Circana US. Formerly IRI and NPD, Circana is a leader in providing technology, AI and data to fast-moving consumer packaged goods companies, durables manufacturers and retailers seeking to optimise their businesses.